
Finance for buying a business

Found a business to buy? We arrange the funding for any trading business in the UK.

The pharmacy. The garage.
The restaurant on the corner. Make it yours.

You know the business. We know the lenders.

How business acquisition finance works
Map of Great Britain

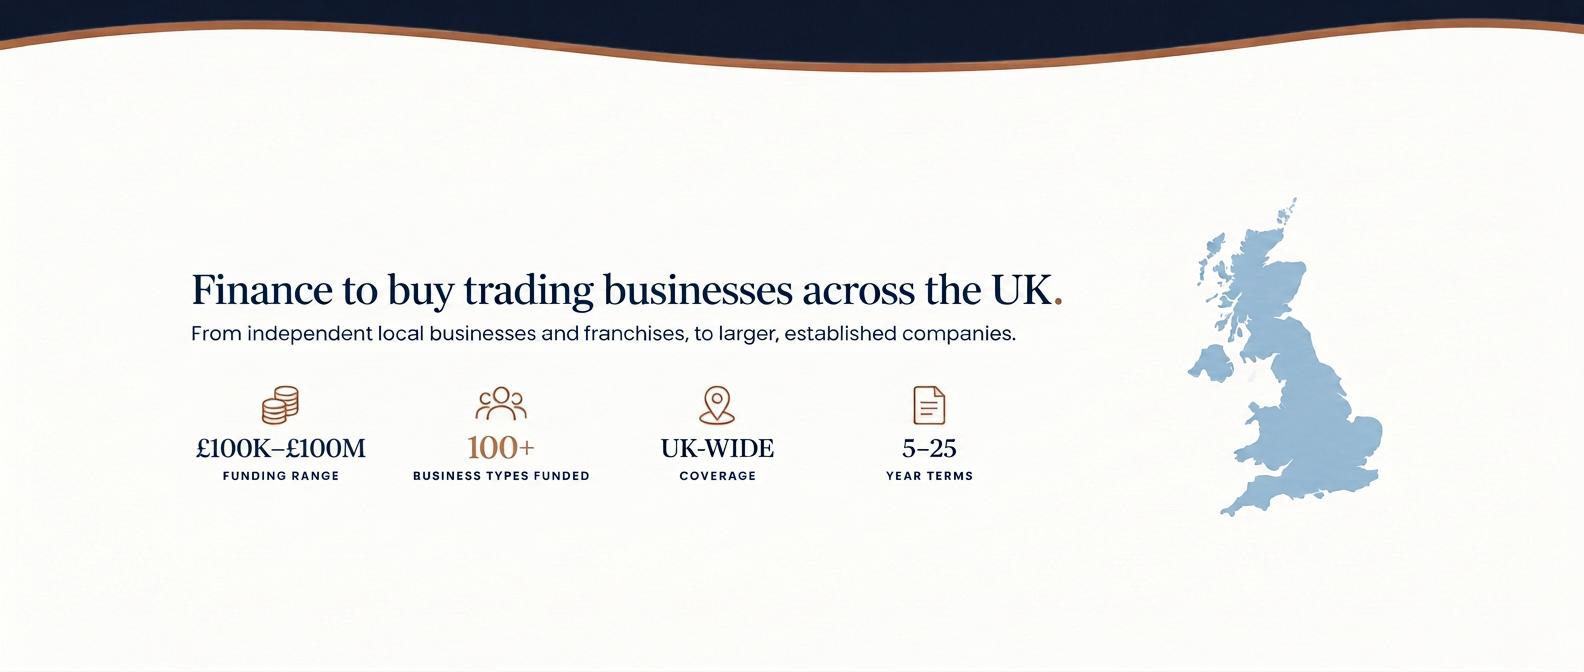
Finance to buy trading businesses across the UK

From independent local businesses and franchises, to larger, established companies.

Funding range
£100K–£100M
Business types funded
100+
Coverage
UK-wide
Year terms
5–25

The approach

Three chapters between you and the keys.

01

The Discovery

You have just found the business you want. You tell us all about it.

02

The Finance

You need financing to buy the business; we find the money.

03

The Completion

We stay by your side through to legal work completion and the business is yours.

Which Businesses can we fund?

The short answer is:Almost any business that’s trading

Our funding isn’t tied to a list of industries. From restaurants and garages to care homes and accountancy practices — if a business has customers, cash flow and a future, we arrange the finance to buy it. Every sector carries its own quirks, and we speak them all.

The iLendi Six™ — the six factors every lender assesses

Lenders want to lend.
They just need confidence.

Confidence that the business is viable, the buyer is capable, and the borrowing can be repaid as agreed. Before we approach any lender, we work with you to gather the information a strong funding application needs — identifying the strengths of your proposal and addressing any concerns in advance.

The iLendi Six™ comprises the six key factors lenders assess when considering an application to fund the purchase of a business — and how we strengthen each one.

What lenders will ask for

Lenders take a close look at the target business to understand its historic trading performance. They'll usually ask for the last two years' certified accounts, recent management accounts, corporation tax returns and business bank statements — and, where applicable, an independent business valuation. If the purchase includes a property, they'll also ask for a property valuation and building survey.

How we strengthen your application

As well as presenting these documents, we prepare supporting information that highlights the business’s achievements, financial stability and recent developments — the context that explains its current performance, future trends and prospects.

Six key factors. One stronger funding application.

Discuss your application

Begin your funding process

Start with a conversation.

Tell us what you want to buy and an experienced funding specialist will call you back same day to discuss how we can help.

Other ways to contact us

Send an email:enquiries@ilendicapital.co.ukCall us: +44 (0)20 3488 8126
WhatsApp us: 07902 282673

We'll open WhatsApp with: "Hello iLendi Capital — I'm looking at buying a business and would like to talk."

Attach files (optional)

You may attach documents here — target business sales particulars, financial accounts, business plan, other relevant documents.

Prefer to message us? Chat on WhatsApp.

Opens WhatsApp with: "Hello iLendi Capital — I'm looking at buying a business and would like to talk."

Before you buy

A few things worth thinking about.

Thirty years of combined experience of the team, distilled into the questions that protect a buyer — asked before you commit, not after.

02Acquisition Finance and Loans

The Costs of Buying a Freehold Business

The purchase price is only part of what you'll spend. Stamp duty, surveys, solicitors, stock and the cash to get through your first month — here's the honest full list, with a worked example.

10 min readRead
04Acquisition Finance and Loans

The Costs of Buying a Leasehold Business

The price you agree with the seller — the lease premium — is only part of it. Rent deposits, landlord's fees, stock and the cash to survive your first month: the honest full list, with a worked example.

10 min readRead

Case studies

Ten sticking points. Ten completions.

To every funding problem, there's a solution. Real deals, real obstacles — and how we got each one completed.

Restaurant

£410k

The sticking point

The buyer had the deposit and the plan — but the bank's valuation came in £50,000 lower, and it demanded loan security the buyer did not have.

The way past it

We applied for Government-backed financing through an alternative lender — one that required no loan security. Their valuation matched ours, and a strong application was approved.

The result: the acquisition completed.

Read the case study

Off Licence

£285k

The sticking point

A first-time buyer with no retail track record — the first two lenders declined on experience alone.

The way past it

On our recommendation, the buyer recruited a full-time manager with six years' experience. We returned to the lender with the strengthened application — and the lender was satisfied.

The result: the acquisition completed.

Read the case study

Launderette

£220k

The sticking point

The weekly takings were healthy, but it was a new company less than two years old — no long track record of stable income to show a lender.

The way past it

We helped the buyers write a strong Business Plan — realistic cash-flow projections demonstrating comfortable affordability of the monthly repayments, supported by growing service-wash contracts. The lender was satisfied.

The result: the acquisition completed.

Read the case study

Beauty Salon · Pet Shop · Flat

£1.45m

The sticking point

A manager of nine years buying the freehold of the salon she ran — but the seller also owned the pet shop next door and the flat upstairs, and wanted to sell the lot. She applied to her bank; after five nervous weeks, it declined.

The way past it

She came to us in a hurry. We prepared a strong application with a lender that has an appetite for mixed commercial property — and secured her 80% funding within ten days.

The result: the acquisition completed.

Read the case study

Garage

£775k

The sticking point

A freehold garage with an MOT contract — but the buyer only had half the required deposit available in cash.

The way past it

We helped the buyer raise the remaining deposit with a loan against his other garage business — using the strength of one business to buy another.

The result: the acquisition completed.

Read the case study

Pizzeria

£360k

The sticking point

A franchise resale with strong takings — but the lender's offer came in below the amount applied for, leaving the buyer £35,000 short.

The way past it

We negotiated a new deal with the seller: the remaining £35,000 paid within six months. Three months after the buyer took ownership, we helped them secure a loan on the strength of the business itself — and the seller was paid in good time.

The result: the acquisition completed.

Read the case study

Computer Rentals

£530k

The sticking point

The assets were laptops and servers — equipment that depreciates faster than most lenders like to fund. Not much security for the bank, which said no.

The way past it

We built the case on the contracted rental income rather than the kit itself — recurring revenue a lender could underwrite — backed by a robust Business Plan with financial projections proving affordability. Our lender said yes.

The result: the acquisition completed.

Read the case study

Self Storage

£2m

The sticking point

A trading site with expansion land. The lender's offer plus the buyer's deposit still left £85,000 short of the asking price — and the deal was stalling.

The way past it

We approached the seller and renegotiated the deal itself: they agreed to wait eighteen months for the shortfall — seller finance, agreed directly between the two parties, at the full asking price.

The result: the acquisition completed.

Read the case study

Pharmacy

£625k

The sticking point

NHS income is gold to the right lender and opaque to the wrong one — the first bank priced it like an ordinary shop, offering a 65% loan, with security. The buyers needed 85%, without security.

The way past it

We placed it with a lender that understands pharmacy income, on terms that reflected the business's track record. Accepted under the government-backed loan scheme: 87% funding, no security required.

The result: the acquisition completed.

Read the case study

Nursery

£920k

The sticking point

A busy nursery, established eight years, suffered a kitchen fire and was forced to close as unsafe. The client needed 70% funding — plus the money to refurbish before reopening. The bank declined.

The way past it

Armed with a detailed Business Plan and cash-flow projections, we approached a lender who looked to the future — and approved the loan. The nursery was refurbished, rewired, reopened — and got even busier.

The result: the acquisition completed.

Read the case study

Repayment Estimator

What would it take to buy it?

This is a free business mortgage calculator when buying the freehold of a business property. Use this calculator to work out your monthly repayments. You can view both your repayment options, Capital and Interest mortgage, or Interest Only mortgage.

£600,000
20%
20 yrs
%

Repayment basis

For illustration only.

Deposit needed

£120,000

Amount financed

£480,000

Est. monthly repayment

£3,168

Capital is repaid month by month — nothing left owing at the end of the 20-year term.

Rates from 4.5%, depending on status and lender. For illustration only.

The loan is only part of it — stamp duty, legals, stock and working capital. Work out the true cost to complete